Where most FinTech products start
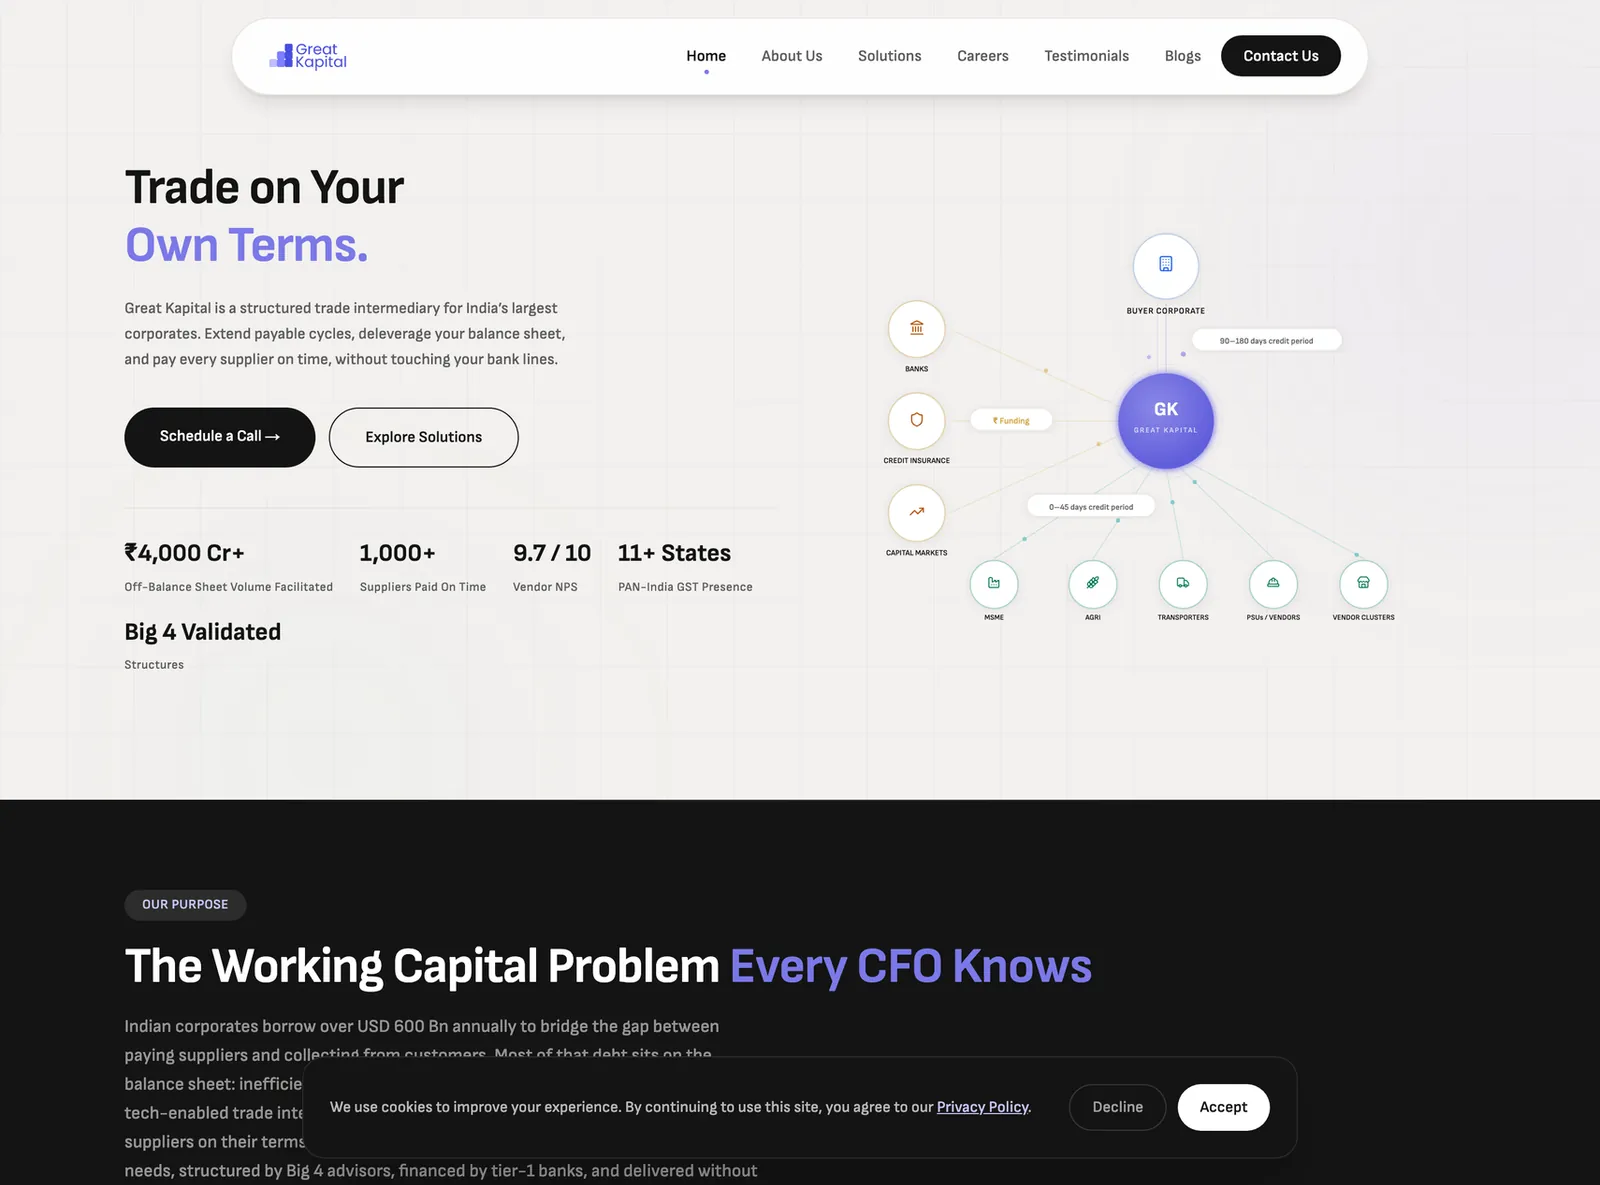
In FinTech the hard part sits under the screens: bank connections, payment flows that reconcile, and the compliance that a partner bank or auditor will ask about. We built a supply chain finance platform for Indian corporates and the bank-data layer behind a personal finance app.
What's different about building FinTech
Real bank data, cleaned up
Plaid account linking, transaction sync and category rules tuned to how your users think about money, so the app works off their real spending, not guesses or rough estimates.
Payments that have to add up
When money moves on someone's behalf, every amount needs a clear trail from request to settlement. We build the ledger and reconciliation first, then the screens.
Compliance is part of onboarding
KYC, tax and audit rules decide how a fintech product onboards people. We build those rules into the data model from day one, not bolted on in a hurry before an audit.
Your partners own the licence
Most startups build on licensed partners: banks, payment providers, data aggregators. We build the platform around their rules, so it fits what your partners expect from day one.
How it works
- 01
Scope and architecture (week 1)
On free calls we map where money and data move and fix scope and price before you pay. Week 1: data model, access rules and audit trail.
- 02
Build (weeks 2-5)
Integrations, payment flows and the screens on top, with working software every week. The engineer building it is the one on your calls.
- 03
Launch and support (week 6 on)
We ship to production, hand over the code, docs and credentials, and stay on for 6 weeks of support while real transactions run.
Starting at $12,000
A FinTech v1 is an MVP Sprint: fixed scope and fixed price, agreed before the build. Need a security review before a partner signs? Start with a Security Audit (from $1,000).
Talk about your FinTech product  rebuilt our onboarding, shipped our Zapier integrations, and wrote integrated plugins for our proprietary tools - all in record time. He ships better than we spec. This team is literally an extension of mine.
Work we've shipped
How we can help
Four ways to work with us - pick what fits, switch when it doesn’t.
Audits
Find what's broken - or whether AI is worth it - before you build.
Learn moreMVP Sprint
Zero to production in 5-6 weeks. A real product, not a prototype.
Learn moreRetainer
A senior engineer embedded on your team, month to month.
Learn moreCode Rescue
Vibe-coded app breaking under real users? We rebuild it to hold.
Learn moreFAQ
Frequently asked questions
How much does it cost to build a FinTech app?
A first version with bank linking, payments or onboarding is an MVP Sprint: one fixed price, agreed before the build. Sprints start at $12,000. We scope it to what your first version needs, from compliance to integrations and partner requirements, and agree the price before the build starts.
Who handles licences and regulatory approval?
You and your licensed partners, such as banks and payment providers, with your own legal advisers. We build the platform to fit their rules, including KYC, audit trails and access controls.
Which integrations have you built?
Plaid for bank linking and transaction sync, Stripe for payments, and custom payment and compliance layers, like the working capital engine and vendor portal we built for a supply chain finance platform.
Do you build FinTech for the US and India?
Yes. We have built finance products for users across the US and for businesses across India. We work with founders in the US, UK, Europe and Australia.
Can you build to our compliance requirements?
Yes. Tell us what applies to you, whether that's PCI, KYC, GDPR or local financial rules, and we build the technical side to match: access controls, encryption, audit logs, where data is stored and which vendors you use.
Do we own the code?
Yes, 100%. You own the code, infrastructure, docs and credentials.